
Following the financing: A wider lens on IG private credit
Investment-grade (IG) private credit does not exist in isolation. Borrowers increasingly have multiple markets available to finance the same business, asset or investment program, with options spanning public bonds, private placements, securitized structures and other financing channels.
For IG private credit investors, we believe this makes a broader view across fixed-income markets increasingly valuable. Understanding how issuers and assets are being financed elsewhere can provide additional context for assessing relative value, diversification and lender protections within the private market.
A shifting financing landscape
Over the past several decades, the opportunity set available to investors has shifted meaningfully. The number of publicly listed US companies has fallen by roughly half since the late 1990s, from approximately 8,000 to fewer than 4,000 today.1 Many companies are choosing to remain private for longer, enabling a greater share of growth and value creation to occur outside public markets.2 Private markets have expanded alongside this shift, with more than 1,200 private companies globally now valued above $1 billion.3
At the same time, borrowers have become increasingly flexible in how they raise debt. The choice of financing channel can depend on execution, tenor, pricing, flexibility, structure and investor demand, creating a continuum that includes registered bonds, Rule 144A issuance and traditional 4(a)(2) private placements (often referred to as "IG private credit”), bank financing and asset-backed structures.
Recent transactions illustrate how frequently issuers are moving across that continuum:
- Mars financed its Kellanova acquisition with a $26 billion Rule 144A/Regulation S bond transaction alongside a separate $1 billion traditional private placement.4
- Danaher completed a CHF2.38 billion institutional private placement, complementing previous issuance in the euro and Swiss bond markets.5
- Zayo evaluated both the 4(a)(2) private-placement and securitized markets before using fiber-network securitizations, including a $1.42 billion ABS issuance, to refinance secured corporate debt and fund network investment.6
- QTS has accessed bank private placements, high-grade bonds and more than $4.5 billion of Rule 144A secured-note financing to support data-center growth.7
- Meta's Hyperion data-center financing used an approximately $27 billion investment-grade Rule 144A structure supported by project cash flows and contractual protections.8
- The pattern extends beyond corporations. The University of Michigan has accessed long-dated public revenue bonds, commercial paper and the 4(a)(2) market, while Cleveland Clinic has combined public hospital revenue bonds, commercial paper, variable-rate debt and direct placements.9 10
Across these examples, issuers are selecting among financing channels based on the particular project, asset, maturity, structure or market environment.
For IG private credit investors, this breadth provides useful context. Similar assets, issuers and underlying capital needs can appear across corporate credit, private placements, project finance and securitized markets, creating multiple reference points for evaluating opportunities.
Looking across credit markets
As issuers move across financing channels, activity in neighboring markets can provide valuable information.
- Relative value. Public IG bonds and securitized transactions can provide additional reference points for assessing private opportunities. Comparing pricing alongside credit risk, structure, maturity and lender protections can help investors evaluate the compensation offered by a private transaction relative to available alternatives.
- Diversification. Cross-market visibility can help investors understand the economic exposures underlying different securities. Digital infrastructure, for example, can appear through the bonds of a hyperscaler, a private placement financing a data-center operator, project finance or an asset-backed transaction. Viewing those exposures together can provide a clearer picture of how a new private investment affects portfolio concentration and diversification.
- Covenants and structure. An issuer's financing alternatives can also influence the economics and protections available to private creditors. Understanding activity across adjacent markets can provide additional context when assessing covenant packages, security, reporting requirements and other structural features.
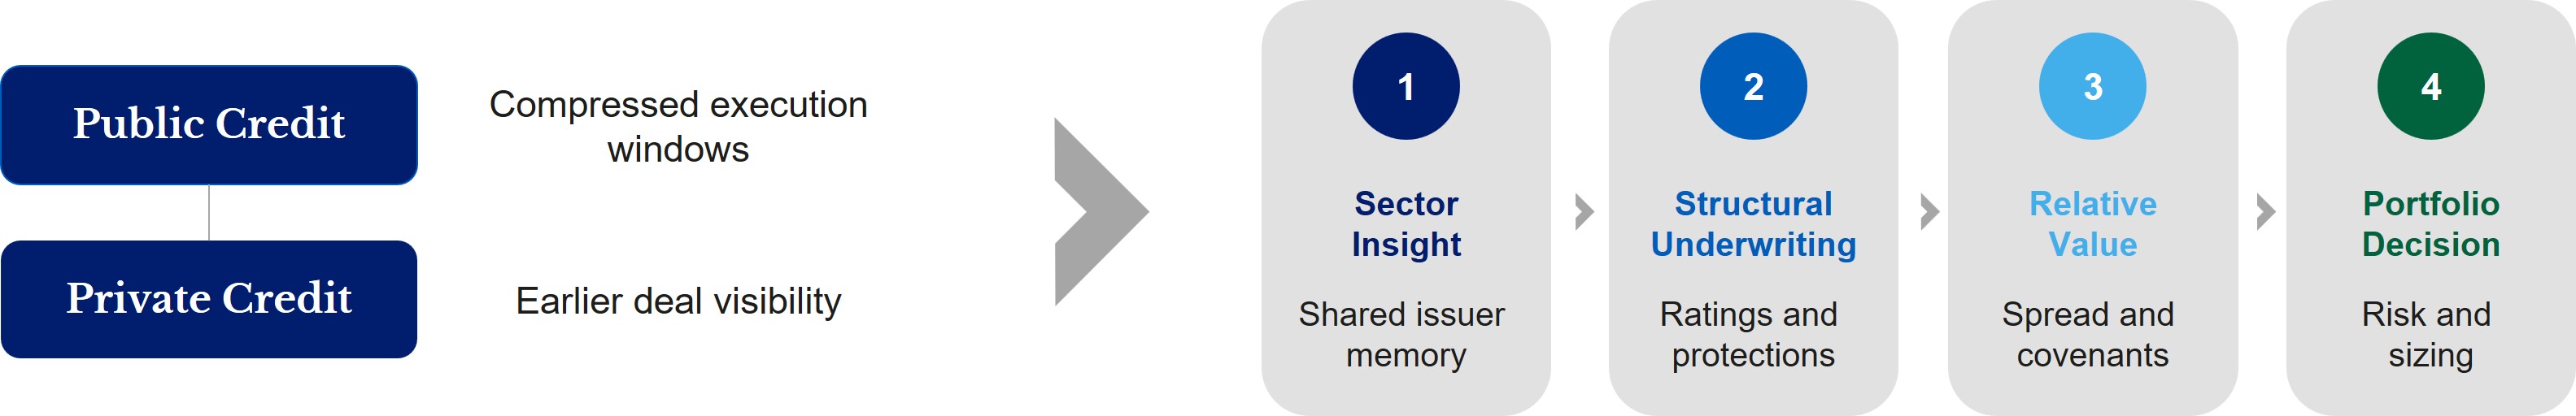
Each market provides a different perspective. Public credit can offer observable pricing and frequent signals on changing perceptions of credit risk. Private placements can provide insight into negotiated structures, lender protections and issuer financing objectives. Securitized markets can offer another perspective on specific assets, contractual cash flows and financing structures. We believe bringing those perspectives together can provide a more complete view when evaluating IG private credit opportunities, deepening the assessment of relative value, diversification and lender protections .
Accessing a wider lens
An effective way to access these multiple perspectives is often to partner with a manager that has long-standing capabilities in both public and private credit. Integrated research teams can identify relative value opportunities across markets, compare issuers regardless of issuance format, and shift capital dynamically as risk-adjusted opportunities change and the financing landscape continues to evolve.
Figure 1: Connected teams drive more informed investment decisions
Public and private perspectives reinforce one another across the full investment process
Source: L&G – Asset Management, America. For illustrative purposes only.
-
Source: Bloomberg. Data as of September 22, 2026.
-
Source: PitchBook.
-
Source: CB Insights, PitchBook.
-
Simpson Thacher, Mars.
-
Source: WilmerHale, Swissinfo.
-
Source: Fitch Ratings, Business Wire / Zayo.
-
Simpson Thacher, New Project Media / Bisnow.
-
Source: The Wall Street Journal, “BlackRock Among the Biggest Investors in Meta’s Giant Data-Center Debt Deal,” October 21, 2025; Forbes, “The Strange Case of Meta,” November 16, 2025.
-
Source: University of Michigan Bonds, L&G Asset Management – America.
-
Source: EMMA / MSRB, S&P Global / MuniChain.
Disclosures
Unless otherwise stated, references herein to "L&G" and “L&G – Asset Management” refer to the global asset management business of Legal & General Group plc. that includes Legal & General Investment Management Ltd. (a U.K. FCA authorized adviser), Legal & General Investment Management America, Inc. (a U.S. SEC registered investment adviser) Legal & General Investment Management Asia Limited (a Hong Kong SFC registered adviser), Legal & General Investment Management Japan KK (licensed by the FAS in Japan), and LGIM Singapore Pte. Ltd. (licensed by the MAS in Singapore). The LGIM Stewardship Team acts on behalf of all such locally authorized entities.
This material is intended to provide only general educational information and market commentary. Views and opinions expressed herein are as of the date set forth above and may change based on market and other conditions. The material may not be reproduced or distributed. The material is for informational purposes only and is not intended as a solicitation to buy or sell any securities or other financial instrument or to provide any investment advice or service. L&G – Asset Management, America does not guarantee the timeliness, sequence, accuracy or completeness of information included. Past performance should not be taken as an indication or guarantee of future performance and no representation, express or implied, is made regarding future performance.
Certain of the information contained herein represents or is based on forward-looking statements or information, including descriptions of anticipated market changes and expectations of future activity. Forward-looking statements and information are inherently uncertain and actual events or results may differ from those projected. Therefore, undue reliance should not be placed on such forward-looking statements and information. There is no guarantee that L&G – Asset Management, America’s investment or risk management processes will be successful.
We have more blogs to share
Visit our blog site to explore our latest views on markets, investment strategy and long-term themes.